
Five stories shaping global markets and business on October 26, 2026.
1. Oil prices ease after a sharp rally
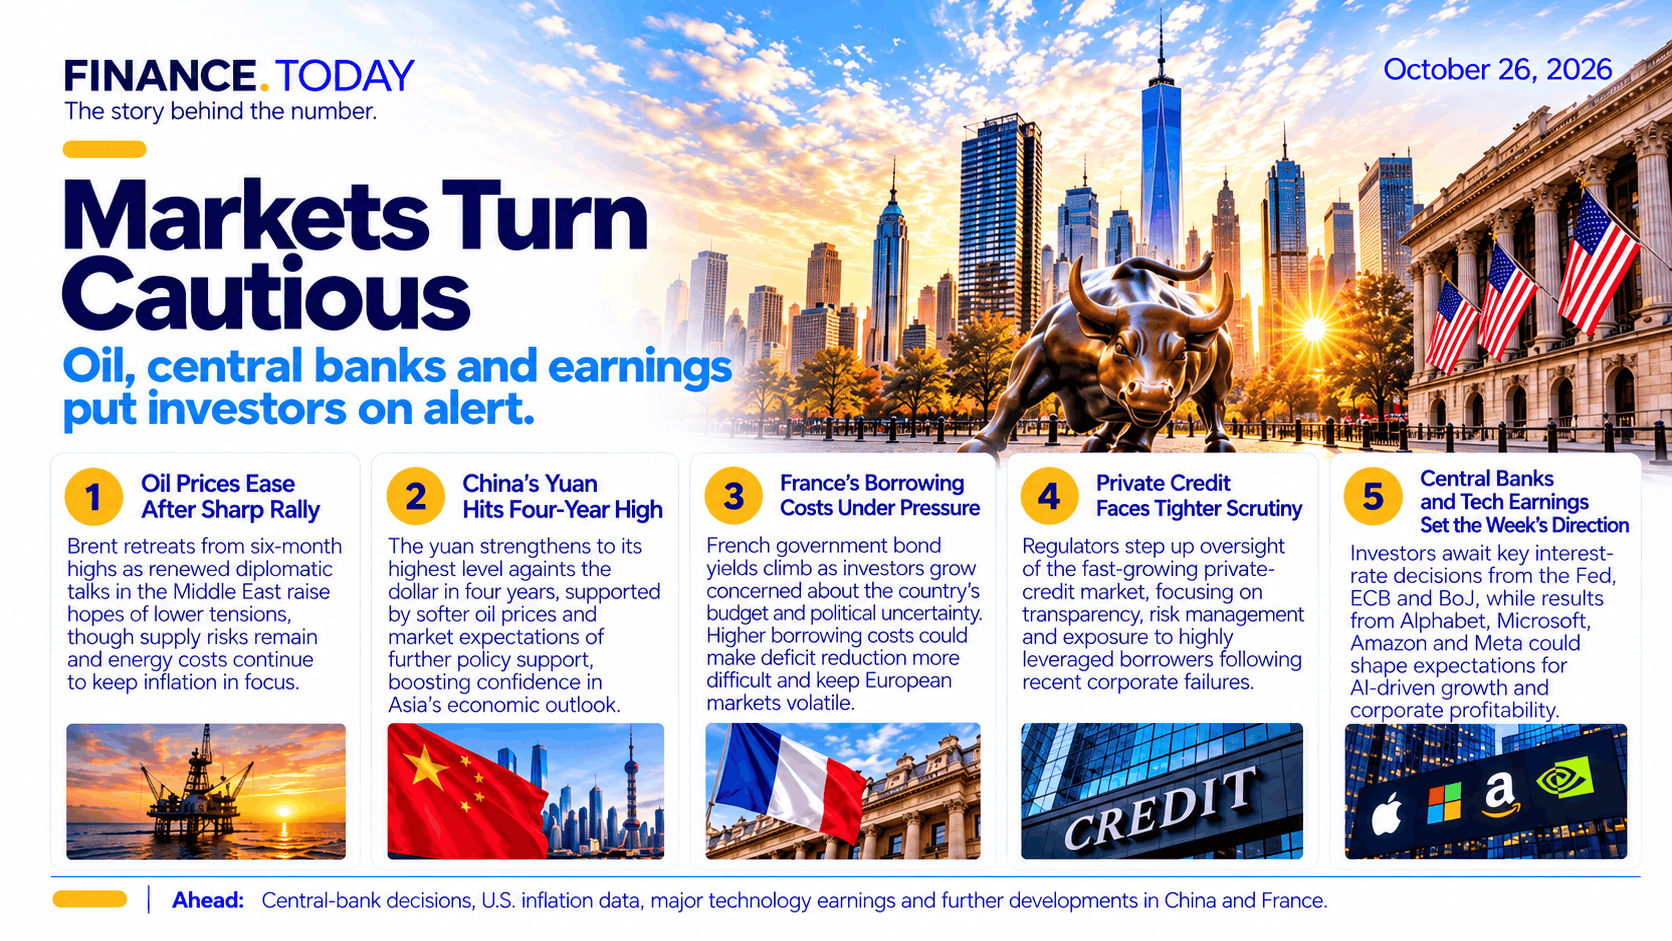
Oil prices retreated on Monday after a sharp rise the previous week, as diplomatic efforts raised hopes of easing tensions in the Middle East. However, concerns about potential supply disruptions continued to support prices. The pullback offers some relief to markets worried about energy-driven inflation, but the outlook remains sensitive to geopolitical developments. If oil prices stay elevated, households and businesses could continue facing higher costs, while central banks may find it harder to bring inflation down.
2. China’s yuan hits a four-year high
China’s yuan strengthened to its highest level against the US dollar in four years, supported by a weaker dollar and expectations surrounding upcoming policy discussions in China. A stronger currency can reduce the cost of imports and signal improved confidence, but it can also make Chinese exports more expensive for overseas buyers. Investors will be watching for policy signals on domestic demand, growth and the wider economic outlook to assess whether the currency’s gains can be sustained.
3. France’s borrowing costs remain under pressure
French government borrowing costs have faced renewed pressure as investors assess the country’s fiscal outlook and political uncertainty. Higher bond yields increase the cost of financing government debt and refinancing existing obligations. If borrowing costs remain elevated, efforts to reduce the budget deficit could become more difficult, potentially affecting spending priorities and economic growth. The situation also matters beyond France, as investors monitor sovereign debt risks and the possibility of wider pressure across European bond markets.
4. Private credit faces tighter scrutiny
Private credit, which provides financing to companies outside traditional public bond markets and bank lending channels, is attracting greater regulatory attention. Concerns include transparency, underwriting standards and how risks are assessed in less liquid markets. Closer oversight could improve safeguards and make risk-taking more visible, but it may also increase compliance costs for lenders. For investors, the key issue is whether rapid growth in private lending has been matched by sufficiently strong risk controls and reliable information about borrowers.
5. Central banks and technology earnings set the week’s direction
Markets are preparing for a busy week of central-bank decisions, economic data and major technology earnings. Investors will be looking for clues about the future path of interest rates, while results from large technology companies could help test whether substantial investment in artificial intelligence is translating into sustainable revenue and profits. Any divergence between earnings expectations and actual results, or a change in central-bank messaging, could influence valuations and risk appetite across global markets.
Ahead
Investors will be watching central-bank communications, US inflation data and major technology earnings for clues about the direction of interest rates, corporate profitability and market sentiment. Developments affecting energy supply and France’s fiscal outlook could also remain important sources of volatility.
Sources
Reuters; Financial News London; official central-bank communications and relevant economic data releases.
This digest is for informational purposes only and does not constitute investment advice.
The story behind the number.
— finance.today
